

Quick Summary: Fintech in wealth management is helping firms automate portfolio management, personalize investment advice, streamline compliance, and reduce operational costs. AI, machine learning, blockchain, and cloud technologies are also making WealthTech platforms more accessible, secure, and data-driven. This guide covers the key types, benefits, technologies, features, development process, compliance considerations, and costs involved in building modern wealth management software.
The growing popularity of Fintech in wealth management is changing how firms advise, invest, and serve clients. Technologies such as AI, machine learning, and blockchain are helping firms:
- Automate portfolio management
- Personalize investment advice
- Streamline compliance checks
- Improve client experiences
- Reduce operational costs
This shift is driving the growth of WealthTech, or wealth management technology. CMARIX breaks down the key categories, benefits, features, development steps, and costs involved in building a modern WealthTech platform.
New technology is also reshaping financial software development services across the financial sector. For wealth management firms, the focus is increasingly on using technology to personalize advice, streamline operations, and make asset management more cost-effective.
What Is Fintech in Wealth Management?
FinTech in wealth management involves the use of technology through software, data, and automation in providing advice and managing portfolios. Examples include robo-advisors, client portals, analytics engines, and compliance software. Companies adopt these solutions to reach more customers cost-effectively.
In practice, fintech wealth management reduces manual work by using connected systems. This gives advisors access to all financial data in one place. Customers have live dashboards, goal-setting, and notifications. The wealth management advisors spend more time giving advice.
The World Bank’s Fintech and the Future of Finance report discusses how digitization is reshaping markets, regulation, and supervision.McKinsey published their findings for fintech, highlighting how it jumped 177 percent to $92.3 billion in 2021. However, they also noted it was a one-off, since funding dropped to $55 billion in 2022. This highlights the advantage companies that ship real products have.
AI is the story now. MSCI’s Wealth Trends 2026 survey shows that 95% of firms plan to raise AI investment. Of those, only 27% believe wealth management leads other financial segments in AI adoption. It is important to understand how to optimize your AI ROI if you are planning to raise AI investments too. Check out the CMARIX AI ROI Frameworkbefore planning your next AI investment.
What Is Driving Wealth Management Digital Transformation?
Three forces drive wealth management digital transformation: client expectations, cost pressure, and AI maturity.
- Investor expectations: investors demand app-based interaction, instant responses, and goal-based recommendations.
- Cost pressure: automation reduces costs associated with trading, reporting, onboarding, and servicing low-margin customers.
- AI maturity: fintechs use machine learning to score risks, rebalance investments, and take the best action.
Trust is key here. A 2026 survey by Advisor360 of 300 advisors found that 74% believe AI will help their business. However, 93% need final control over the AI product decision, and 55% say compliance is the biggest challenge. As a result, the best platforms keep a human advisor in the loop.
Three Main Categories of Fintech in Wealth Management
McKinsey’s Asia-Pacific WealthTech research sorts firms into three archetypes by who they serve.
- Direct-to-consumer WealthTechs (D2C). These platforms sell advice and portfolio management straight to retail investors online. Clients can access ETFs, mutual funds, real estate, and startup investments. The aim is affordable, personalized advice for a wider audience.
- WealthTechs for financial institutions (B2FI). These vendors sell banks and asset managers the tools to modernize. Examples include client portals and back-end links across the value chain. Modular platforms let an institution upgrade one service or the whole process.
- WealthTechs for financial advisors (B2FA). These firms build digital tools that help advisors work faster. Automation takes over admin work, so advisors can spend more time with clients. Fintech for financial advisors also gives clients a smooth way to track investments.
Benefits of Fintech Solutions for Wealth Management
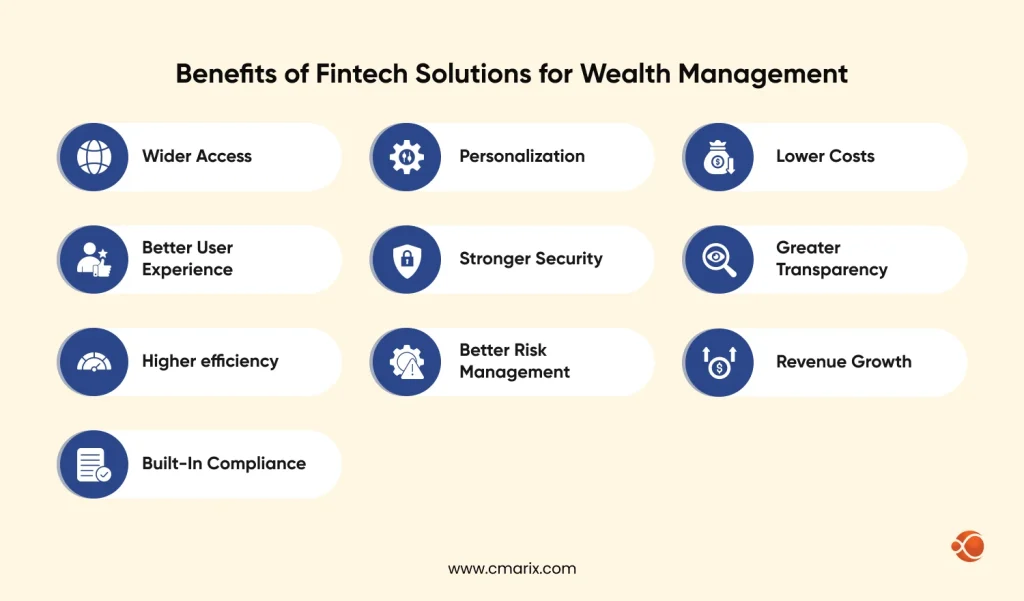
Digital wealth management solutions make old methods faster, cheaper, and more transparent. Here are the ten fintech benefits in wealth management that firms and clients notice first.
| Benefit | How It Helps |
| Wider access | Low minimums and mobile onboarding put wealth services within reach of more investors, wherever they live. |
| Personalization | Algorithms match portfolios to goals, risk tolerance, and liquidity needs, while alerts keep clients engaged. |
| Lower costs | Automating trading, reporting, and operations trims infrastructure and staffing costs. Firms can pass savings on to clients. |
| Better user experience | Clean dashboards, instant alerts, unified account views, and advisory chatbots make investing simpler. |
| Stronger security | Biometric login, multi-factor authentication, and end-to-end encryption help protect client data. |
| Greater transparency | Open APIs and automated reporting show holdings, fees, and performance as they change. |
| Higher efficiency | Fewer errors, faster transactions, and greater scalability allow firms to grow without matching headcount increases. |
| Better risk management | Exposure calculations, cash flow models, and stress tests support more informed decisions for complex products. |
| Revenue growth | API-based platforms let firms open new channels and monitor client activity in real time. |
| Built-in compliance | KYC checks, AML monitoring, and fiduciary controls can run within onboarding and advice workflows. |
Core Technologies Behind Wealth Management Technology
- AI for wealth management: AI generates suggestions, detects risks, and provides next-best actions. Generative AI describes portfolios and client meetings. This has already been tested and proven in banking and digital transformation.
- Machine learning: Machine Learning ranks risk, detects fraud, and forecasts client churn. Predictive Analytics consultation can turn those insights into forecasts advisors can rely on.
- Blockchain technology for wealth management: Blockchain ensures security and transparency for tokenized assets, enables faster processing, and provides non-repudiable transaction logs. If you choose blockchain, hire expert blockchain developers.
- Open APIs and cloud: APIs allow integration with custodians, banks, and third-party data providers. Cloud infrastructure scales up as demand grows.
- Cybersecurity and identity: Use encryption, biometrics, and continuous monitoring across systems and processes.
Features to Include in a WealthTech App
Investors expect more than a portfolio view. Build these into the first release, or at least the roadmap, of any fintech wealth management product.
- Portfolio management through automated plans and real-time market information
- Tools for financial planning such as long-term forecasts, savings schemes, and budgeting
- Tax management services that include tax-loss harvesting and tax-aware investing
- Retirement planning using savings calculators and customized solutions
- Monitoring portfolios in real time with alerts about risks and trends
- Goal-setting tools with goal trackers and reminders
- Custom analytics and reporting
- Aggregating accounts from banks, brokerage firms, and other systems
- Chat-based support services with access to human advisors round the clock
- Secure data management based on encryption, multi-factor authentication, and auditing
Which fintech app ideas should you develop? Combine these modules according to your market needs. The neobank app development process includes many common flows, including onboarding and KYC. Are you developing technology for WealthTech startups? Stay modular.
How to Develop a Wealth Management App
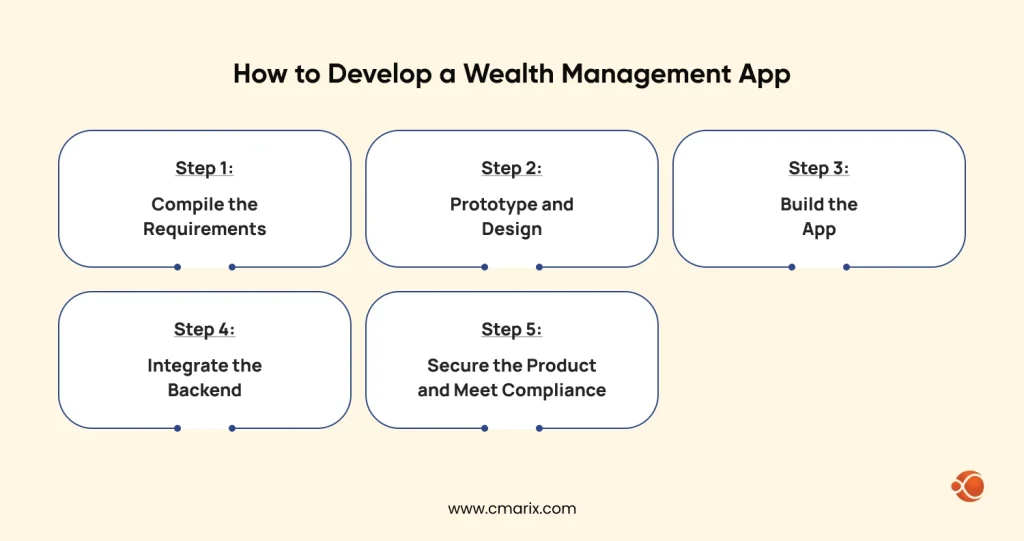
Step 1: Compile the Requirements
Begin by discovering what your users really need. This means talking to prospective users, running surveys, and testing prototypes to identify the features that matter most. Such features could be multi-account management, rebalancing, planning calculators, an AI recommendation system, safe fund transfers, and reporting. As for the planning engine, refer to our article on building custom planning software.
Step 2: Prototype and Design
Convert them to wireframes and flows. Set a visual direction and create a testable prototype. This will give you insight into confusing screens and unnecessary actions that could arise during development.
Step 3: Build the App
Select a tech stack that matches your platform and product requirements. Platforms like React Native let you develop for iOS and Android without creating two separate codebases. After you build the core application, connect your market data feeds and any required third-party API integrations. If the platform supports active trading strategies, you will also need proper trading logic. Our guide to custom algorithm trading software covers this in more detail.
Step 4: Integrate the Backend
Ensure integration with back-end systems that support the application. Ensure your architecture is scalable in the cloud and that you integrate the advisers’ tools with the customer relationship management systems of large organizations. Integration with trade execution engines, portfolio accounting systems, bank and brokerage systems, and account aggregators may also be necessary.
Step 5: Secure the Product and Meet Compliance
Ensure that your product is secure and compliant from day one rather than making it compliant when it is almost ready for deployment. Be aware of all the regulations applicable to your advice-giving platform, such as advisers’ regulations, privacy laws, and GDPR if it applies. Make sure you cover security and logging for your activities.
Step 6: Launch, Test, and Support
Start with a beta launch of the platform available for testing by a small group of users. Observe user behavior and improve the platform. Keep on doing the same even after the actual launch of the platform.
Compliance and Trust: What Regulators Expect from Digital Wealth Platforms
Regulators expect automated advice to meet the same duties as human advice. Treat compliance as part of the product.
The Financial Industry Regulatory Authority (FINRA) Report on Digital Investment Advice dates back to 2016. It highlights concerns like algorithm governance, customer profiling, conflicts of interest, and portfolio rebalancing. It also mentions that digital means do not eliminate conflicts of interest.
Failure enforcement demonstrates the consequences of failure. In June 2022, the SEC filed charges against three advisory subsidiaries of Schwab for failing to disclose robo-advisor practices. These companies said the amount of cash was optimized for clients; however, Schwab’s calculations showed clients earned less money under almost all market conditions.
Three habits protect you on any digital wealth platform:
- Say plainly how your platform earns money.
- Document how each algorithm makes decisions.
- Test models before launch and after every change.
At CMARIX, we build these controls into our architecture from the first sprint.
How Much Does Wealth Management Software Development Cost?
As a basic guide, the price guide for mobile banking app development at CMARIX puts MVPs around $45,000. Full digital banking platforms cost over $600,000. Wealth platforms require the same kind of security and integration, so the price guide is useful for early planning.
Five things move the budget most:
- Number and intricacy of functionalities
- Level of AI and analytics
- Integrations with custodians, banks, and data providers
- Scope of security and compliance
- Location and engagement of the team
The Future of Wealth Management Technology
Four shifts will shape fintech in wealth management over the next few years.
- Hyper-personalization: AI will provide tailored advice based on each client’s goals, risk tolerance, and life stage.
- Agentic AI: The field is moving away from generators to use agents that perform certain tasks with the advisor’s approval.
- Tokenization: blockchain-based assets promise fractional ownership and faster settlement.
- Interactive interfaces: richer data visualization and immersive views will make portfolios easier to grasp.
Why Choose CMARIX for WealthTech Development?
Wealth platforms usually stumble in two places: the compliance review and the first real integration with a custodian. We’ve spent 16+ years in banking software development, so we plan for both before design starts.
Our teams cover AI, machine learning, blockchain, cloud, and compliance in a single engagement. You don’t have to coordinate a data science vendor, a security auditor, and a mobile team yourself. That matters more here than in most fintech. A robo-advisor’s recommendation logic, its audit trail, and its disclosure screens all have to agree with each other, and they rarely do when three separate vendors build them.
When you build with us, you get:
- A platform that fits your model. Advisor tools, institutional systems, or a D2C app for a startup, each built from the modules your market needs.
- AI and predictive analytics in the core, with a human advisor keeping final control over every recommendation.
- Auditable architecture. We document how each algorithm decides and test models before launch and after every change. These controls go in during the first sprint, not the week before go-live.
- Engagement models that follow your roadmap. Start with an MVP and add modules as your client base grows.
Conclusion
Fintech in wealth management rewards firms that build trust into the product from day one. If you’re planning a platform, scope the compliance and AI-review steps before you pick features. CMARIX can help you plan, build, and scale it. Speak with our WealthTech experts to scope your build.
FAQs About Fintech in Wealth Management
What is the impact of fintech in wealth management?
Financial technology reduces costs, broadens accessibility, and makes financial advice more personalized. Automation handles trading, reporting, and onboarding, saving advisers from administrative work. Customers receive real-time information and goal-based financial planning. Financial regulations remain the same for financial advice.
What are the latest core trends in wealth management technology?
AI is the biggest one. MSCI reports that 95% of firms plan to increase AI investment. Other trends include agentic workflows, hyper-personalization, open APIs, tokenized assets, and built-in compliance. Firms are also keeping advisors in control of AI output.
How is blockchain technology changing data security in wealth management?
Blockchain helps to keep tamper-resistant records. Each transaction is timestamped and cannot be changed, thus making auditing easier. Smart contracts help automate certain conditions. It does not replace other security features like encryption and monitoring.
What is driving wealth management digital transformation?
Consumer needs, budget restrictions, and AI technologies. Investors require applications first. Companies have to serve small customers well. Advanced AI can automate research and analysis.
What software options help regional banks compete with wealthtech in wealth management?
Regional banks may choose to use white-label platforms, modular B2FI tools, or custom software. White-label solutions are the quickest to market. Modular tools let you upgrade specific services, such as client portals. Custom software provides control over your data and branding.